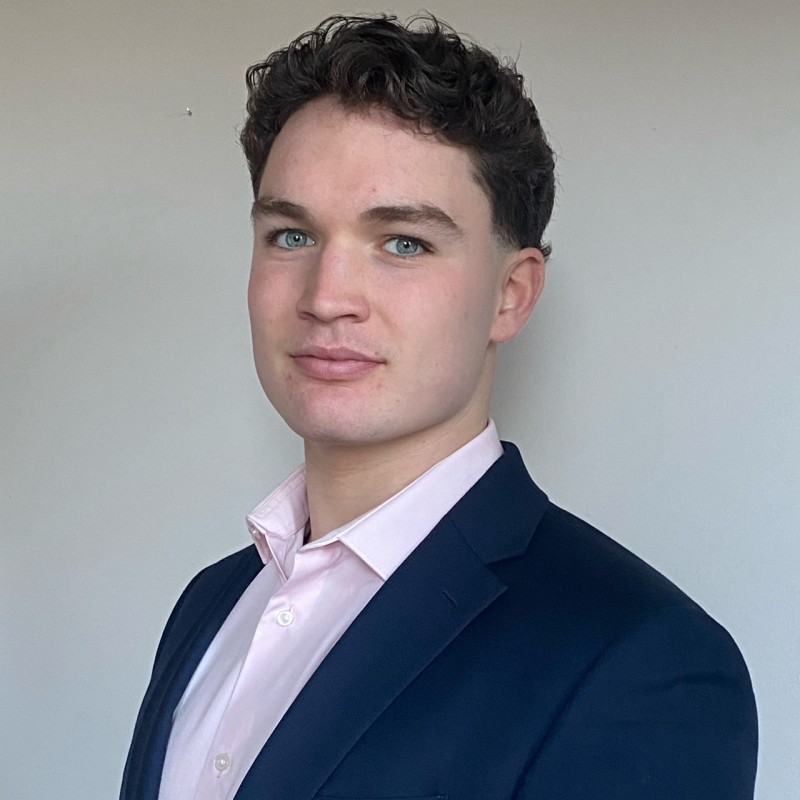
GWGeorge Williams

BSc Economics at the University of Nottingham · Class of 2027

Curious about data.
Serious about credit.

I’m George Williams, an Economics student pursuing a career in Data and Credit. I use quantitative analysis and commercial judgment to understand businesses, assess risk and make evidence count.

Open to graduate opportunities starting in 2027

George Williams

1st class honours71% average to date
BSc Economics - University of Nottingham

2nd placeBarings stock pitch competition

3rd placeNottingham Investment Competition

Manager of the YearNEFS Investment Fund

01 / SELECTED PROJECTS

Analysis you can explore.

From predictive models to lending decisions.
A selection of independent and collaborative work.

02 / CREDIT MODELLING

PYTHON · LOGISTIC REGRESSION · SYNTHETIC DATA

Making credit risk measurable.

A probability-of-default modelling project using synthetic data, developed during my Bibby credit-risk internship.

Explore the approach +

Built a logistic-regression model from data preparation through evaluation and scorecard design. Explored known good and bad outcomes and the treatment of indeterminate cases.

The project demonstrates a modelling workflow; synthetic-data results do not establish performance on a live lending portfolio.

View PD model code on GitHub ↗

03 / INDEPENDENT CASE STUDY

PRIVATE CREDIT · LBO · DOWNSIDE ANALYSIS

Mimecast: a lender’s perspective.

An independent private credit case study examining the business model, recurring revenue, financial statements and downside risks.

Explore the approach +

Combined market and company research with capital-structure analysis, forecasts and an LBO model to support a lending recommendation. Considered protections designed to support recovery in a default scenario.

An independent case study using publicly available transaction information and scenario assumptions.

Read the investment memo ↗

04 / PORTFOLIO STRATEGY

PYTHON · MEAN–VARIANCE · RISK MANAGEMENT

A North American investment strategy.

A collaborative core-and-active equity strategy combining company research with mean–variance optimisation and a defined Value at Risk constraint.

Results & contribution +

Built and back-tested a Python portfolio model within a three-day 2% VaR threshold at 90% confidence. The CV reports S&P 500 outperformance of 4.86% for the competition period and third place in the Nottingham Investment Competition.

Strategy presentation co-authored with Rohan Verma. Historical competition results reflect the stated period.

View the strategy ↗

ADDITIONAL RESEARCH / STOCK PITCH

Vertiv Holdings: the infrastructure behind data centres.

Company drivers, competitive positioning, financial analysis and valuation.

↗

02 / EXPERIENCE

Putting analysis to work.

Credit risk, commercial research
and investment leadership.

JUN — SEP 2026

Bibby Financial Services

Risk Transformation Intern · Credit Risk

Worked primarily in credit risk, analysing portfolio and credit-exposure data in SQL, investigating data quality and presenting scenario analysis through Power BI for a risk committee.

Supported governance improvements and the resolution of five internal audit points. Developed a synthetic PD model and built an AI agent workflow with Excel macros to make underwriting more consistent. End-to-end tests achieved 99% accuracy against policy rules; the workflow was later used for administrative tasks in other business functions, including document content transfer.

Credit riskSQL & PythonAI-assisted underwriting

AUG 2025 — JUN 2026

NEFS Investment Fund

Portfolio Manager · North American Equities

Managed a £21,000 equity portfolio, applying financial and ratio analysis to investment recommendations. Reported S&P 500 outperformance of 3.58% over the management period.

Delivered a DCF and LBO modelling masterclass to 20 analysts and was named Manager of the Year.

Investment researchTeam leadershipFinancial modelling

MAR — APR 2026

Caremixer

Student Strategy Consultant

Delivered a 55-page market research report for a SaaS start-up. Led client liaison and coordinated analysis and recommendations covering the market, client dynamics and usability forecasts.

Market researchClient communicationCommercial analysis

03 / A LITTLE MORE ABOUT ME

Quantitative thinking.
Commercial curiosity.

I’m studying BSc Economics at the University of Nottingham, with first-class honours achieved to date. I’m interested in how data can improve decisions—whether that means understanding a borrower, evaluating a model or making a clear recommendation.

Beyond the analysis, I enjoy bringing people together. As Vice-President of the University’s Men’s Rugby Union Club, I support operations for 200 members and manage the alumni network.

78%Financial Economics74%Microeconomic Theory73%Applied Econometrics II

MY TOOLKIT

Data & modelling

Python · SQL · Excel · Stata · Power BI
Predictive modelling · Econometrics · Back-testing

Credit & finance

Credit-risk analysis · Financial statements
Scenario analysis · Capital structure · Valuation

Working with people

Stakeholder presentations · Report writing
Client liaison · Team coordination

↗
Barings University Stock Pitch Competition

Second place · February 2025
Research, valuation and a pitch to the judging panel.

04 / WHAT’S NEXT

Let’s start a
conversation.

I’m exploring graduate opportunities in Data and Credit for 2027.
If my work connects with yours, I’d love to hear from you.